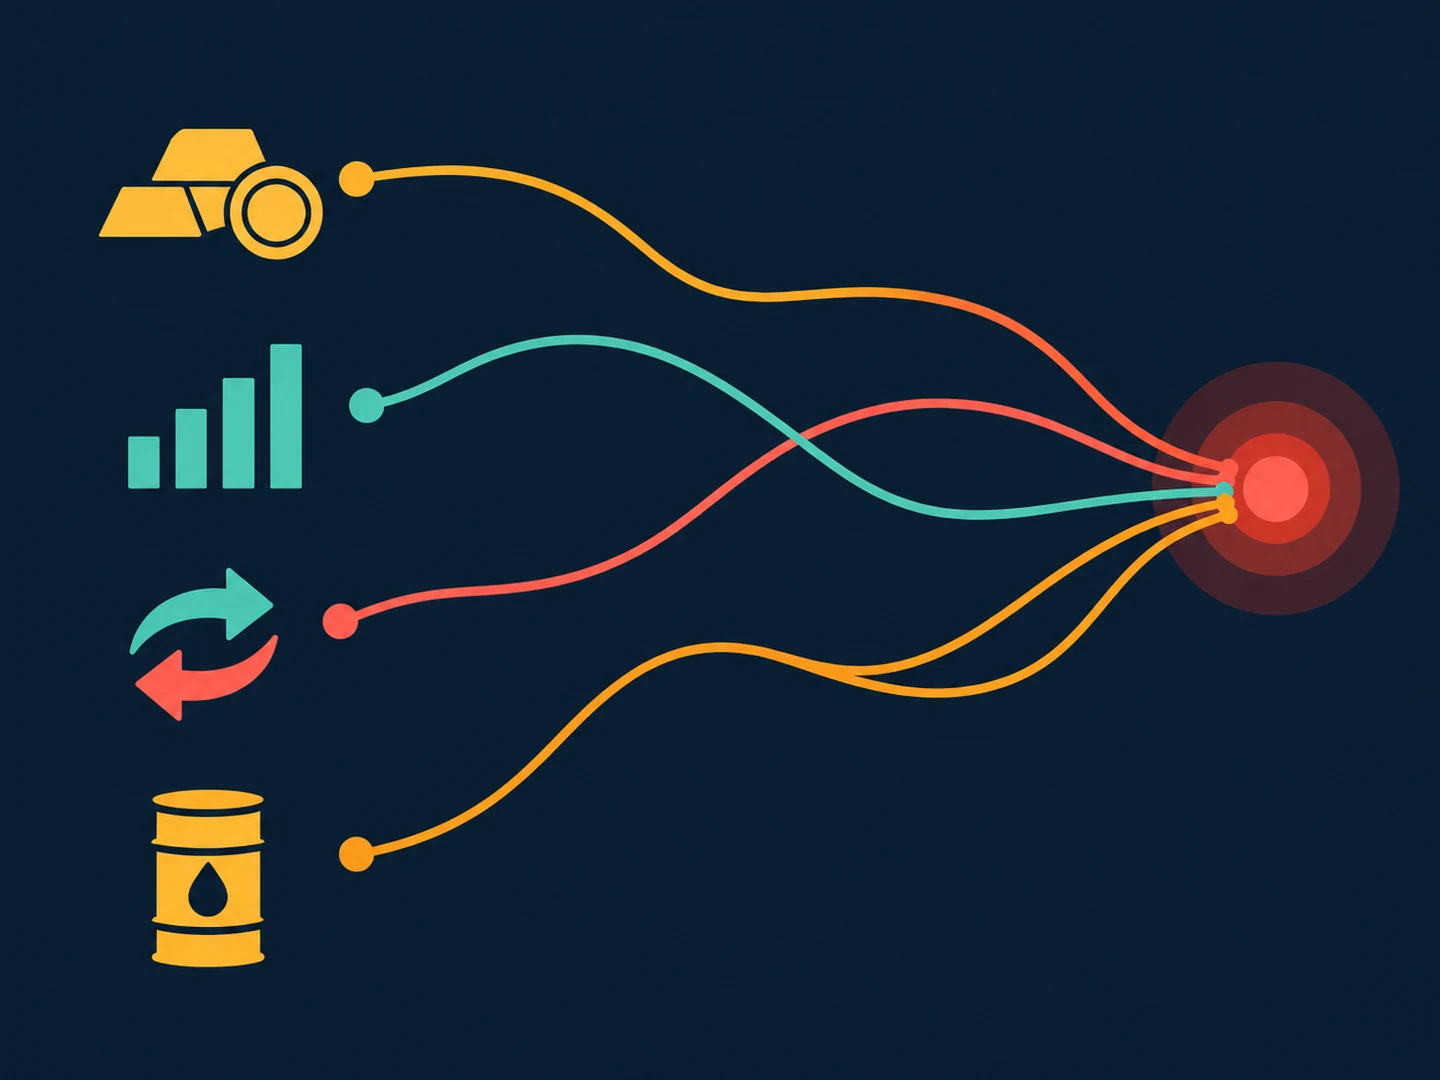
A list of positions can look diversified because it contains different names, products, or timeframes. Yet several entries may respond to the same underlying driver. When those exposures move together, the portfolio can behave more like one concentrated position than the labels suggest.
This is why portfolio risk is not simply the sum of each position's standalone risk measure. The interaction between positions matters. A useful review asks what common sources of movement exist, how those relationships were estimated, and which assumptions could fail at the same time.
Why does standalone risk miss portfolio interactions?
A position-level measure describes one exposure in isolation under a chosen model. Aggregating several measures as if each exposure were independent can miss covariance: the tendency of outcomes to move together or in opposite directions over the sample being studied. Portfolio variance is represented by the weight vector, covariance matrix, and their interaction, often written as w-transpose Sigma w.
The formula is a framework, not a promise that a sample covariance matrix captures every kind of risk. It depends on what returns, horizon, weights, and data window were used. It also describes variability under its assumptions, not every loss mechanism, liquidity constraint, gap, operational problem, or model failure a portfolio may encounter.
Names are not the same as independent drivers
Two different instruments can share exposure to a common factor, while two similar-looking instruments may behave differently in some periods. Asset labels are a weak proxy for dependence. A review can group exposures by the economic, market, or operational drivers that might affect them, then ask whether the apparent diversification survives those groupings.
This is a conceptual map, not a recommendation to own or avoid any instrument. For a hypothetical portfolio, several positions might all rely on a narrow condition such as stable liquidity, a particular volatility environment, or the same underlying sector. If that condition changes, the exposures may not provide the offset their separate labels imply.
Understand covariance before reading a single total
Covariance and correlation describe different scales of co-movement. Covariance is measured in the units of the two variables; correlation standardizes the relationship to a bounded scale. Neither is a fixed property independent of the sample. A correlation calculated from one window can differ from another because the window, regime, volatility, and data quality differ.
The portfolio weights also matter. An exposure with modest standalone variability can have meaningful influence when its weight is large or when it is strongly related to other exposures. Conversely, a low observed correlation does not guarantee protection. Estimation error, nonlinear behavior, and extreme observations can make simple historical summaries incomplete.
Look for concentration beyond position count
Count alone can be misleading. Review concentration by size, common factor, source of return, liquidity, time horizon, or operational dependency. A portfolio with many small components may still depend on a single fragile assumption. A short inventory of shared drivers often explains more than a long inventory of symbols.
- Exposure size: how does each component contribute under the chosen measure?
- Common driver: which conditions could affect multiple positions at once?
- Data and model: do the estimates rely on the same sample or assumptions?
- Liquidity and timing: could several exposures need to be adjusted under similar conditions?
- Tail behavior: what might happen outside the ordinary variation represented by the estimate?
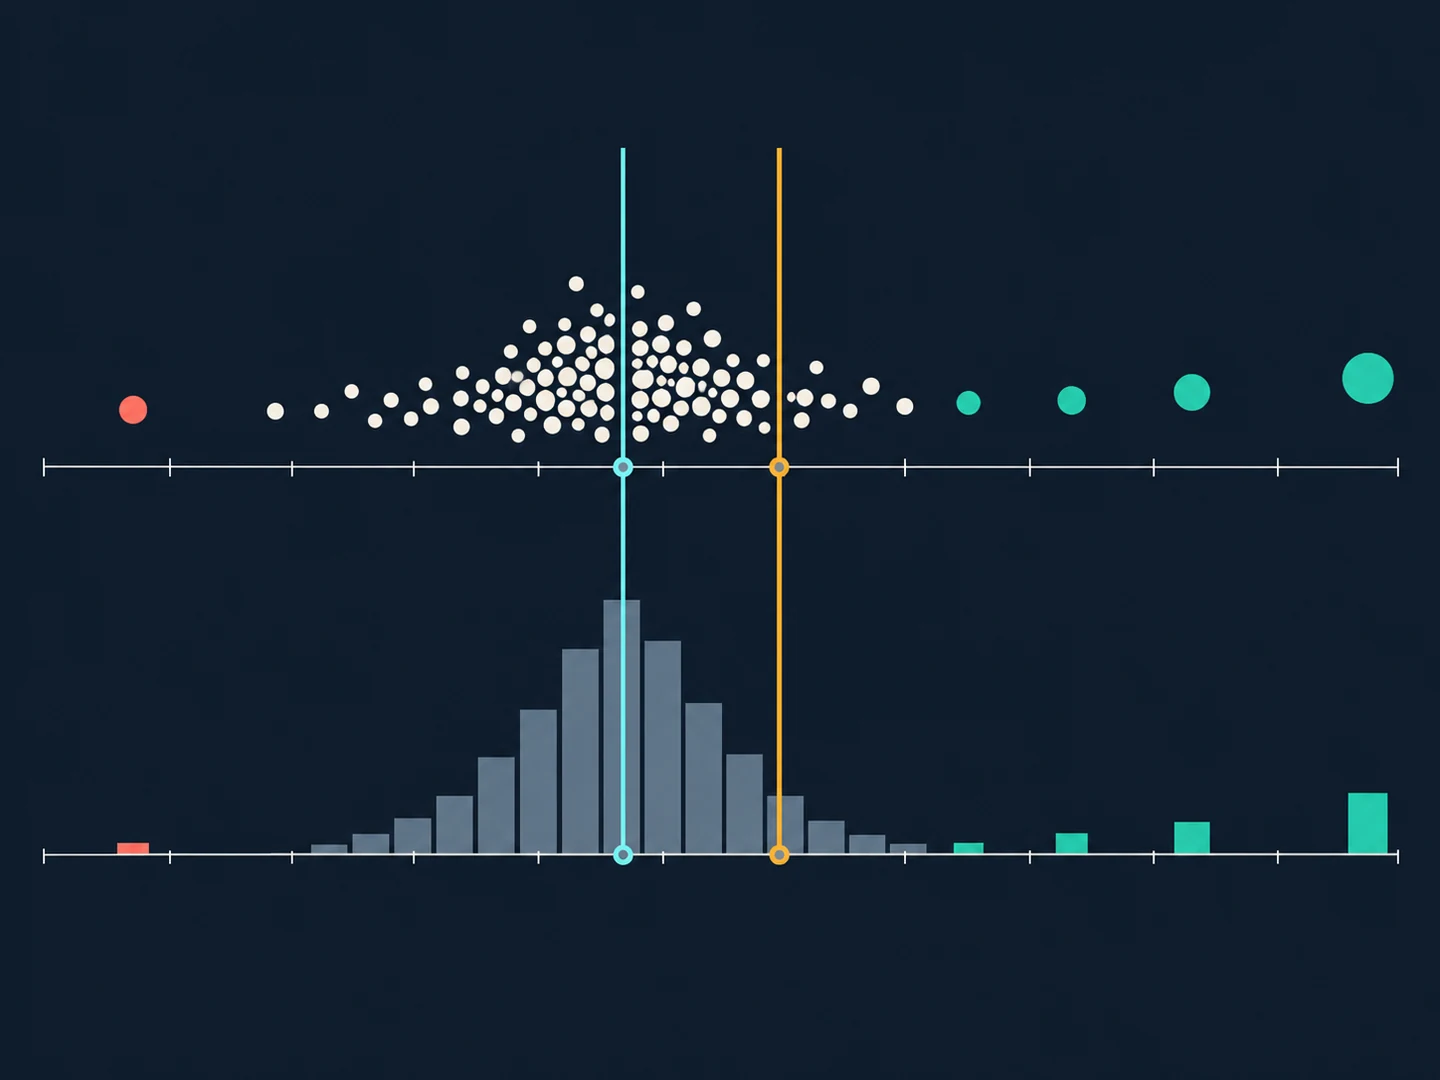
This review should preserve uncertainty. A driver map does not prove that two positions will move together next time, and a matrix does not describe every joint outcome. It makes dependencies visible enough to question. If the answer changes under a reasonable alternative window or grouping, that sensitivity is part of the evidence.
A useful companion to the matrix is a plain-language dependency register. For each exposure, note the drivers that may be shared with others and the evidence supporting that link. Mark whether the relationship is directly measured, inferred from a proxy, or simply a scenario worth testing. This prevents a neat quantitative table from lending false certainty to a qualitative assumption.
The register should also identify what could make the estimated relationship unreliable: short histories, different trading hours, stale prices, or a change in how the instruments are constructed. These details are easy to omit when a single covariance estimate is copied into a presentation. Recording them beside the estimate keeps its limits visible to the next reviewer.
Stress assumptions, not just the center of the sample
Stress analysis asks how conclusions change under specified disturbances. A simple exercise might increase estimated dependence, widen the range of returns, or model a period in which liquidity is reduced. These are scenarios, not forecasts. The assumptions should be stated before the result is interpreted, and the exercise should not be presented as a prediction of a particular crisis.
A stress scenario is useful when it exposes a dependency that a normal-period average hides. It is less useful when the inputs are chosen only to generate a dramatic number. Keep a record of why each scenario was selected, what it omits, and whether the result is driven by one exposure or by an interaction across several.
Keep measurement limits in the report
Historical covariance is estimated from observations that may be short, overlapping, revised, or drawn from a different environment. Missing data and mismatched timestamps can distort the matrix. Aggregating returns at one interval may also conceal sequencing and intraperiod behavior. A concise report should name the period, frequency, return definition, weighting method, and any known gaps.
Do not let one portfolio number stand in for every risk question. Variance does not directly answer how large a drawdown can be, whether a position can be liquidated, whether a margin requirement changes, or whether a strategy is suitable for someone. Separate the measures and avoid treating any historical statistic as a guarantee.
A practical portfolio review sequence
Start with the objective and unit of analysis. List positions and their weights, map plausible shared drivers, estimate dependence using a documented sample, and compare a small set of pre-defined alternatives. Then inspect stress cases and the assumptions behind each. The sequence makes it easier to see whether a conclusion comes from position size, correlation, a data choice, or a particular model.
The result should be a clearer description of the portfolio, not a directive to add or remove an exposure. State what the analysis reveals, what it does not measure, and which conclusions are sensitive to assumptions. If a decision requires personal objectives or financial circumstances, a general educational framework is not a substitute for individualized professional advice.
- Read about mean and median trade outcomes
- Audit look-ahead bias in historical tests
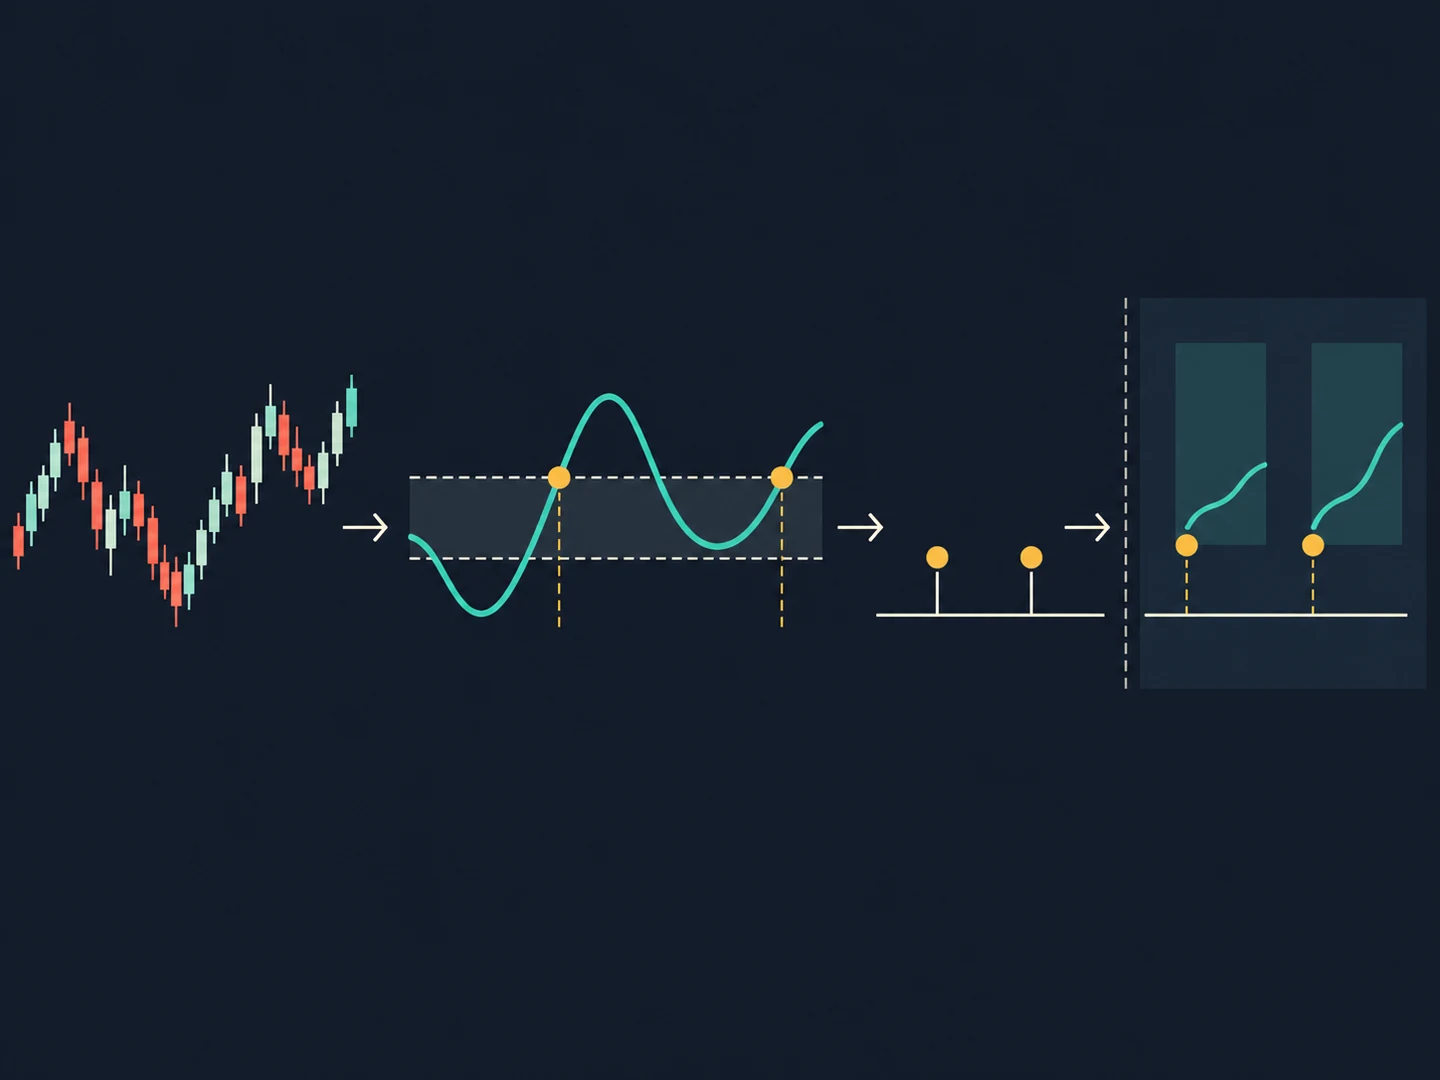
- Turn an indicator into a testable rule
Sources and further reading
- Mean Vector and Covariance MatrixNIST/SEMATECH e-Handbook of Statistical Methods